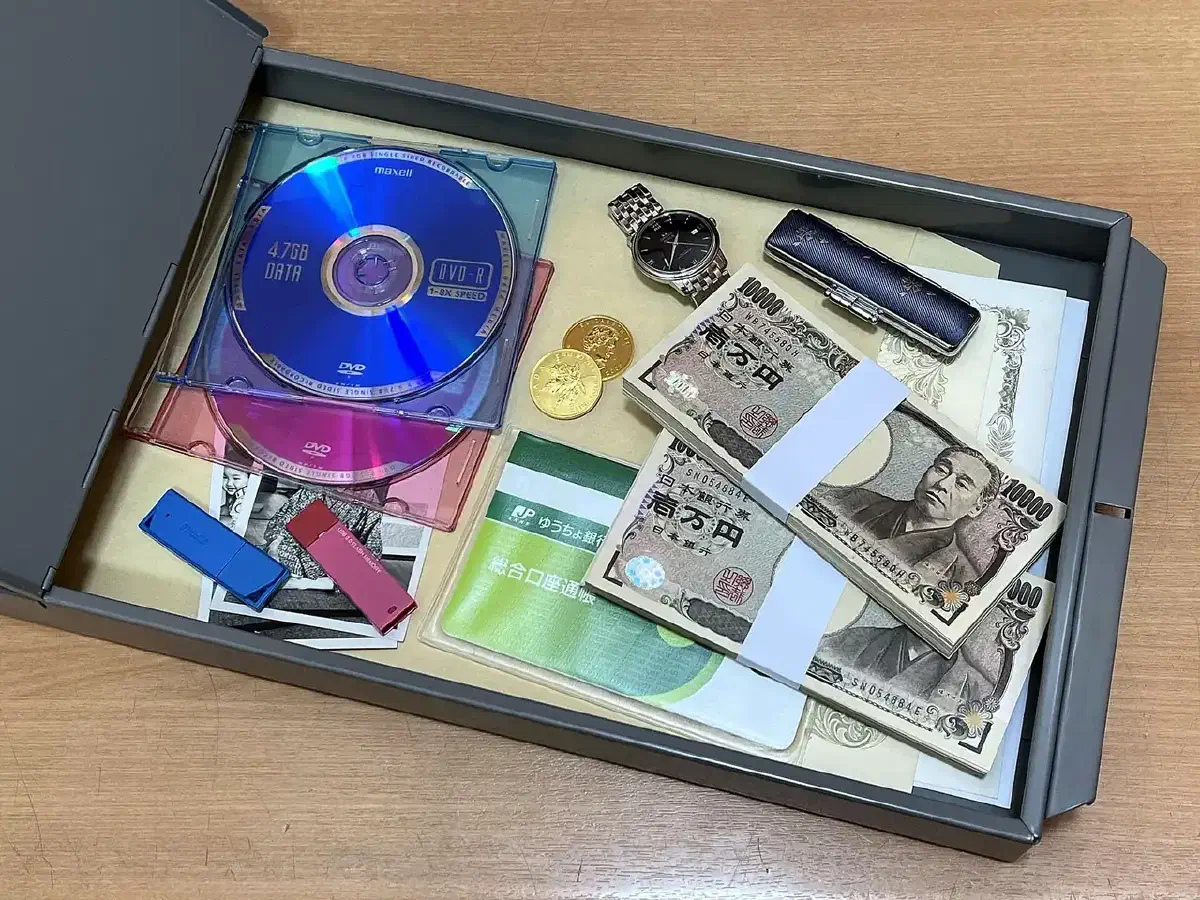
A pantry full of food and a good water filter won’t help much if a job loss, a medical bill or a run of bad markets drains your accounts first. Financial preparedness is the same discipline as any other kind of prepping: find the weak points, build a buffer, and review it on a schedule. The difference is that most of the work is paperwork, and you can start tonight.
This checklist moves from the everyday basics (know your numbers, build the emergency fund) through protection (insurance, income, debt), growth (investing, retirement, estate planning), and finally the harder question of what financial skills matter if the system itself is damaged.
1. Know where you stand #
You can’t plan around numbers you haven’t looked at. Sit down with a few hours and a spreadsheet or notebook.
Income and expenses. List every income stream, including your job, side work and anything else that pays. Then list every expense: bills, groceries, entertainment and discretionary spending. Track your spending habits for at least a month so you are working from real figures rather than guesses.
Assets and debts. List savings accounts, retirement funds, investments and real estate, then list credit card balances, student loans, mortgages and any other liabilities. Subtract one from the other and you have your net worth, which shows you the big picture.
Credit report. Review it regularly and make sure the information is accurate and up to date.
From this you can build a realistic budget and set goals that fit your actual situation. A budget is also the first prepping tool, because it tells you what you can afford to stock, learn and save.
2. Build the emergency fund #
An emergency fund is a savings account set aside for unexpected costs such as medical bills, car repairs or a sudden job loss. It is a cushion that keeps you from going into debt, or from selling investments at a bad moment, when something goes wrong.
Set the target. Aim for three to six months of living expenses. Add up your monthly essentials (bills, groceries and other necessary costs) and multiply by three or six, depending on how much security you want. People with a single income or variable pay should lean toward the high end.
Keep it separate. Open a dedicated account so you aren’t tempted to spend it on non-essentials, and choose a high-yield savings account with competitive interest and easy access. A separate account also makes progress easy to track.
Automate. Set up automatic transfers from your checking account so you contribute consistently.
Start small if you have to. If six months of expenses sounds overwhelming, begin with a smaller goal and raise it over time. Use the fund only for true emergencies.
3. Protect your income #
Losing your job or taking a major pay cut hurts as much as any disaster. Consider disability, life and unemployment coverage to protect your income if something unexpected happens.
Then diversify. Relying on a single paycheck is a vulnerability. Look at side work, freelancing, consulting or a small business, and over time at passive income from rental property, dividends or royalties. Several modest streams are sturdier than one large one.
4. Get the right insurance #
Insurance turns a catastrophic loss into a manageable one. Review your health, life, home, auto and disability policies, and make sure coverage limits are adequate and policies are current. Increase limits where the gaps are real.
Depending on your situation, you may also need umbrella insurance, which provides extra liability coverage beyond standard policies. Long-term care, identity theft and pet insurance are worth considering in the right circumstances. Review your coverage regularly, since needs change.
Disaster-specific coverage is its own subject. Standard homeowners policies typically exclude flood and earthquake damage, so see our guide to disaster insurance for homeowners. If cash is the constraint, prepping on a budget is the place to start.
5. Deal with debt #
High debt makes every emergency worse. List each debt with its balance, interest rate and minimum payment. Then choose a method. With the debt avalanche you pay off the highest-interest debt first while making minimums on the rest. With the debt snowball you pay off the smallest balances first for momentum. Either works if you stick to it.
Other moves: make extra payments on high-interest debt, consolidate or refinance to lower your rates, negotiate with creditors for lower rates or payments, and avoid taking on new debt unless it is truly necessary. If you are struggling, a credit counseling service or financial advisor can explain relief options. Keep an eye on your credit score and utilization ratio. A higher score qualifies you for better loan terms and lower interest rates.
6. Invest for the long term #
Investments are what turn savings into security. Spread money across stocks, bonds, mutual funds and real estate so that a downturn in one market doesn’t wreck the whole portfolio. Diversification is the single most effective protection against volatility.
Start early so compounding has time to work. Use tax-advantaged retirement accounts such as a 401(k) or IRA. Know your risk tolerance and time horizon, stay informed about market trends and economic indicators, and consider a financial advisor to develop a strategy that fits.
7. Plan for retirement #
Retirement may feel far off, but it rewards early starts. Contribute to your employer-sponsored plan, such as a 401(k) or 403(b), and consider an IRA to supplement it. Aim to save at least 15% of your income. Think about the life you want in retirement and estimate costs for housing, healthcare, travel and essentials, then adjust the savings goal to match.
8. Protect your estate #
Estate planning is part of financial preparedness, not an afterthought. Draft a will that says how you want your assets distributed. Consider a living trust to avoid probate and smooth the transfer to your heirs. Designate beneficiaries for retirement accounts, life insurance policies and other assets, and review those designations regularly, especially after marriage, divorce, births or deaths in the family. Out-of-date beneficiaries cause confusion and disputes.
9. Prepare for economic instability #
Global economic instability means uncertainty in the financial markets, often driven by currency swings, trade tensions between nations or political unrest. In such periods stock markets can fall sharply, inflation can rise, and currencies can lose value. If your home currency weakens, your savings buy less. If markets fall, your portfolio loses value.
Beyond the steps above, a few habits help:
- Assess your risks. Look at your income sources, debt levels and exposure to market swings, and decide where you are most vulnerable.
- Educate yourself. Follow financial news, market trends and economic indicators. Attend seminars or consult an advisor if you want to understand them better.
- Stay calm. Fear leads to impulsive decisions that turn temporary losses into permanent ones. Step back, assess rationally and get advice before making major changes.
- Think long term. Fluctuations are a normal part of the investment cycle, and short-term losses may be offset over time.
- Get professional guidance if you feel overwhelmed. An advisor can assess your finances and build a tailored strategy.
Hyperinflation is the extreme case, and it has its own response; see our guide to surviving economic hyperinflation. For a hard-asset hedge, read about the role of precious metals in prepping. The getting started guide places all of this in the larger plan.
10. Tie money to prepping #
Financial independence means having enough personal wealth to live comfortably without depending on a job. For preppers it overlaps with preparedness: both are about securing your future and shielding yourself from unforeseen events.
Wealth funds your preparations. Savings and investments pay for supplies, equipment and training. Budgeting and frugality work in both worlds: track expenses, live below your means, and put resources toward essentials rather than extras. Skills have a financial side too. Growing your own food, fixing things around the house and providing first aid make you more self-sufficient and cut your costs. Courses in gardening or permaculture, first aid or CPR training, basic carpentry, plumbing and electrical work, and joining a local prepping group are all worthwhile.
A simple version of the money-and-prepping link is worth stating: every dollar you don’t have to spend in an emergency is a dollar of resilience.
11. If the financial system fails #
Suppose the damage goes beyond a bad market. In a post-collapse financial landscape, a different set of skills matters.
Budgeting and financial management. Even without banks, you need to track what you have, what you use and what you can spare. Living within your means matters more when no credit is available.
Bartering and trade. Traditional currency may lose its value, so negotiating trades, valuing goods and services, and building relationships with other traders become essential. See bartering skills and goods for a collapse.
Alternative investments. Stocks and bonds may become worthless, but you can still invest in commodities such as food, water or fuel, and in skills and knowledge that will be in demand.
Asset valuation. Know the value of tangible assets (real estate, precious metals, physical possessions) and intangible ones (skills, knowledge, relationships), and manage them wisely.
Self-sufficiency. Producing your own food, generating your own energy and purifying your own water reduce dependence on fragile financial systems.
Community. Networks of mutual support share resources, skills and knowledge, and make a group more resilient than any one household.
Risk management. Assess risks, plan contingencies and adapt fast. A resilient mindset is as useful as any asset.
12. Keep it current #
Financial preparedness is a continuing process, not a one-time task. Life changes, goals change and economic conditions shift, so the plan has to change with them. Put a financial check-in on the calendar each month: review the budget, emergency fund, insurance coverage, debt repayment plan and investments. Stay flexible, adjust when circumstances change, and stay committed.
The checklist at a glance #
- Net worth calculated; budget written
- Emergency fund of three to six months’ expenses in a separate high-yield account
- Insurance reviewed (health, life, home, auto, disability, umbrella if needed)
- Debt list with a repayment method chosen
- Credit report checked
- Income diversified
- Investments diversified; retirement contributions underway
- Will, trust and beneficiaries current
- Financial skills and barter inventory started
- Monthly review scheduled
Do the first item this week. The rest follows in order, and each step makes the next one easier.